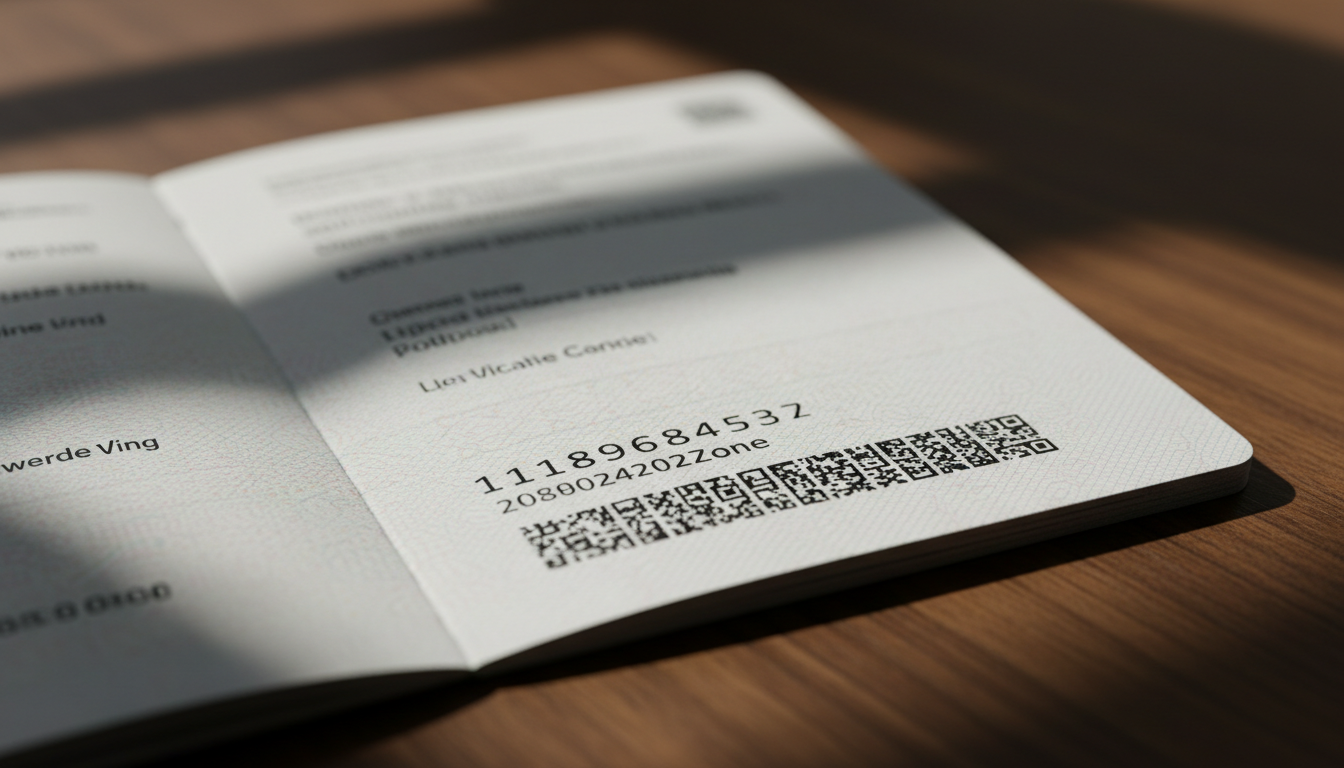
Open personal account online workflows extract identity data from an uploaded passport scan via optical character recognition, changing an unverified image into structured data fields. Manual submission of identity files directly precedes this parsing stage, while automated screening against risk databases and sanctions registries follows it immediately. The extraction step dictates whether the application continues along an automated straight-through route or drops into an asynchronous compliance review queue.
Direct Indicators in the Data Parsing Stage
The transition from a raw image file to structured database records relies on specific machine-readable zones. On standard travel passports and national identity cards, the bottom lines contain chevrons, alphanumeric sequences, and check digits. When an onboarding platform parses this band, it reconciles the calculated checksum against the document number, expiration date, and birth date. A single blur over a check digit breaks the algorithm’s parity calculation.
Observing how an interface populates these extracted strings provides immediate clues about system accuracy. If the software misidentifies diacritics, truncates compound surnames, or confuses the character “O” with the numeral “0”, it signals that the boundary between mechanical optical recognition and human compliance oversight has already broken down. When an automated parser misreads an alphanumeric field, the downstream query sent to screening watchlists will contain false parameters, triggering either a false positive flag or an outright rejection.
Infrastructure Beyond the Intake Form
Once identity fields clear the parser, the onboarding pipeline shifts from document ingestion to payment architecture. A user interface typically presents a uniform dashboard, but the underlying account relies on segregated operational layers:
- Identifier Assignment: The allocation of a unique International Bank Account Number (IBAN) or domestic sort code tied to a specific balance ledger.
- Clearing Rails: The communication networks through which incoming transfers settle, such as SEPA Instant, Target2, or local automated clearing houses.
- Safeguarding Protocol: The segregation of customer deposits into designated credit institution accounts, distinct from the operating capital of the financial technology provider.
These elements determine how balances move once active status is granted. A service might present an immediate account dashboard, yet withhold full outgoing settlement capacity until secondary checks resolve behind the interface.
Where Standard Onboarding Logic Fails
Automated verification rules operate on the premise that proof of residence matches the jurisdiction of the applicant’s primary identity document. This assumption fails routinely for cross-border contractors, expatriates, and cross-border telecommuters. When a person holds a passport issued by one state but presents a utility bill, residential lease, or tax certificate issued by another, standard matching logic falters.
In this exception scenario, algorithmic parsing engines cannot establish a deterministic correlation between the machine-readable passport data and the localized billing address. The system cannot rely on standardized regional database registers to cross-reference the user’s name against municipal address rolls. As a result, the straight-through onboarding path ceases. The application requires direct manual assessment by a compliance officer who must reconcile jurisdictional validity under specific anti-money laundering frameworks, extending verification timelines from minutes to multiple business days.
Verifying Technical Readiness Before Funding
Before initiating an initial deposit into a newly verified ledger, verify the exact routing details generated in the profile settings. Note the country code embedded in the first two letters of the assigned IBAN and check whether the issuing entity appears on national central bank registries under its own licensed entity name or through a designated technical banking partner. Inspect the account profile to confirm that both incoming and outgoing transaction permissions show active status across the settlement rails you intend to use.